---
title: Greece, play by play
tagline: What was done, what was refused and by whom, 2009–2018 — read from France in 2026
flag: "🏛️"
date: 2026-10-04
author: bzhmacro
status: Working note
sources: ECB, Eurostat, ESM, Eurogroup, Eurex tape
---
# Greece, play by play
The Greek crisis was not one decision but about a hundred, and most of the important ones were refusals. This note keeps the ledger — what was adopted, what was rejected, by whom — lists every instrument the euro area has built since 2008 with the condition that opens it, and lays the same grid over France, where the 10-year spread to Germany went from 69bp on 16 Jul 2026 to 149bp on 2 Oct 2026.
> [!IMPORTANT]
> **The reading in one paragraph.** Greece's problem was solvency and credibility; France's is political capacity. But the mechanisms rhyme: no party will co-own a consolidation, a structural reform was reversed to keep a government alive, and the challenger leading the polls is being priced six months before the vote. The instruments that ended the last crisis are gone (SMP, PEPP reinvestment), gated behind a programme France would have to request (OMT), or gated behind criteria France does not obviously meet (TPI). On the record of 2010–2022 the ECB moves after governments do, and when more than one country is in play. Neither condition holds on 2 Oct 2026.
## The numbers that matter
| | Greece, going in | France, 2025–26 |
|---|---:|---:|
| Deficit, % of GDP | 15.4 (2009) | 5.1 (2025); 5.4 expected 2026 |
| Primary balance, % of GDP | –10.3 (2009) | –2.9 (2025) |
| Debt, % of GDP | 128.5 (2009) | 115.6 (2025); 119 at Q2 2026 |
| Debt, € | 301bn | 3,460bn |
| Debt as share of euro-area GDP | 3.2% | 21.8% |
| Current account, % of GDP | –12.5 | –0.4 |
| Interest bill, % of GDP | 5.1 | 2.2 |
| 10-year yield | 5.5% (Dec 2009) → 29.2% (Feb 2012) | 4.0% (Aug 2026 avg) → 4.96% (1 Oct) |
| Spread to Bund | 235bp (Dec 2009) | 82bp (Aug avg) → 149bp (2 Oct, futures-implied) |
| Rating | BBB+ → CCC | A+ / A+ / Aa3 / AA |
| Rescue fund vs debt | €110bn = 37% | ESM €500bn = 14% |
Sources: Eurostat (EDP notification, balance of payments), ECB long-term interest rate statistics, Agence France Trésor, Reuters, Eurex tape.
## Greece in seven acts
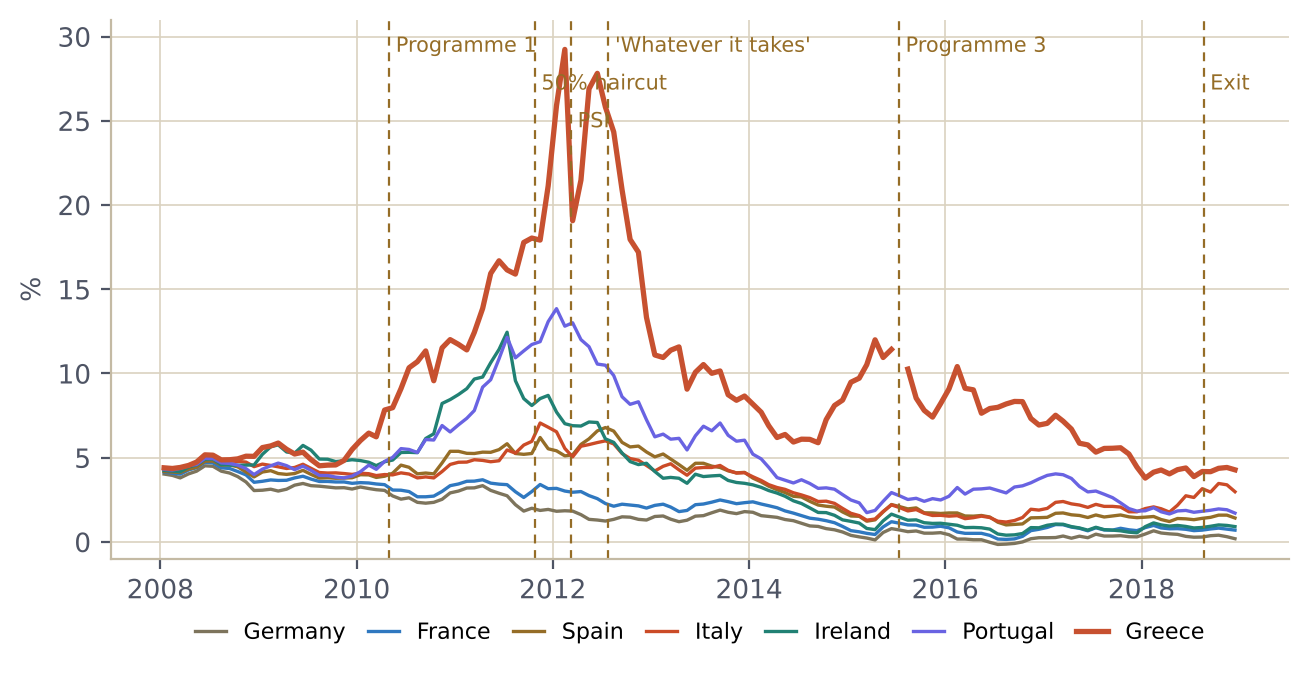
| Act | Dates | What was done | What was refused |
|---|---|---|---|
| Disclosure | Oct 2009 – Apr 2010 | Deficit revised from 6% to 12.7%; three austerity packages; EU statements without instruments | A named support facility (Germany, until after a state election); a European-only rescue without the IMF |
| First programme | May 2010 | €110bn at Euribor +300bp; ECB waives collateral rating floor; €750bn EFSF/EFSM/IMF backstop; SMP bond purchases | **Debt restructuring** (ECB, France, Commission); joint Commission bonds (Germany); announced-size ECB purchases |
| Contagion | Oct 2010 – Dec 2011 | Deauville PSI doctrine; Ireland €85bn, Portugal €78bn; 21% then 50% haircut agreed; ECB letters to Rome and Madrid; two ECB rate rises, then two cuts; 3-year LTROs | Bail-in of Irish senior bank debt (ECB, US); Eurobonds, three times (Germany); an EFSF banking licence (Germany, ECB); Papandreou's referendum (Merkel, Sarkozy) |
| Restructuring | Feb – Dec 2012 | €130bn second programme; 53.5% haircut on €199bn with retrofitted CACs; CDS triggered; 'whatever it takes'; OMT; ESM; November debt relief and buy-back | ECB participation in the haircut; a budget commissioner for Greece (Greece, Commission); an official-sector haircut (Germany, ECB); a €1tn firewall |
| False exit | 2013 – 2014 | Cyprus: depositor bail-in and capital controls; IMF admits 'notable failures'; Greece issues at 4.95% | Levy on insured Cypriot deposits (Cypriot parliament, 0 votes for); Greece's 'clean exit' (creditors, then markets) |
| Syriza | Jan – Sep 2015 | QE without Greece; waiver lifted; ELA capped; banks shut; referendum 61% No; third programme up to €86bn | A bridge programme (Eurogroup); a one-month extension for the vote (Eurogroup, 18–1); Schäuble's five-year 'time-out' (France, Italy, then Merkel); a nominal write-down |
| Relief and exit | 2016 – Aug 2018 | IMF abolishes its 2010 exemption and stays out; ten-year extension on €96bn of EFSF loans; exit with a €24bn buffer | Upfront quantified relief (deferred past two German elections); a nominal haircut — never granted |
Total disbursed: €288.7bn. From first downgrade to investment grade restored: 13 years and 10 months.
## Five refusals that came back
| Refused | When, by whom | What happened |
|---|---|---|
| Restructuring Greek debt | May 2010 — ECB, France, Commission | Done in March 2012 on a smaller private base, after two years of official money repaid private creditors. The IMF called the delay a mistake in June 2013 and abolished the rule that allowed it in 2016. |
| ECB purchases of government bonds | 6 May 2010 — Trichet: 'not discussed' | SMP launched four days later; €218bn bought by 2012. |
| An unlimited ECB backstop | Nov 2011 — Draghi | 'Whatever it takes', July 2012. OMT, September 2012. Never used. |
| Eurobonds | Dec 2010, Nov 2011, Jun 2012 — Merkel | €750bn of joint EU debt in July 2020, once the shock was symmetric. |
| Relief on official loans | Nov 2012 – 2017 — Schäuble | Promised in November 2012 'once a primary surplus is reached'; delivered in June 2018 as maturities, not principal. |
## How the cast moved
| | From | To |
|---|---|---|
| Merkel | No bailout; only as ultima ratio, only with the IMF (2010) | Keeps Greece in against her finance minister (2015); joint EU debt (2020) |
| Schäuble | A European Monetary Fund with state insolvency (2010) | A five-year 'time-out' from the euro (2015) |
| Trichet | No IMF, no default, no collateral exceptions, no purchases | IMF in, three waivers, €218bn bought, letters dictating reform |
| Draghi | SMP is temporary and limited (2011) | 'Whatever it takes' (2012); ELA frozen while Greek banks run (2015) |
| Lagarde | As French minister: no restructuring (2010) | At the IMF: Europe must write down its loans (2012–18). At the ECB: 'not here to close spreads', then PEPP and TPI |
| Samaras | Votes against the first memorandum (2010) | Implements the second (2012–14) |
| Tsipras | Tear up the memorandum (Jan 2015) | Signs the third, harsher, and wins re-election on it (Sep 2015) |
| IMF | Lends under a rule rewritten on the day (2010) | Refuses to lend without debt relief (2015–18) |
Greece changed finance minister nine times between 2009 and 2018; Germany once. Almost every euro-area government that faced voters in 2010–12 lost. PASOK went from 43.9% to 4.7%.
Three people from that cast are in the French story. Christine Lagarde chairs the Governing Council until October 2027. Emmanuel Moulin, Sarkozy's economic adviser in 2009–12, has been governor of the Banque de France since June 2026. And Greece's finance minister, Kyriakos Pierrakakis, chairs the Eurogroup and the ESM's Board of Governors.
## The toolkit since 2008
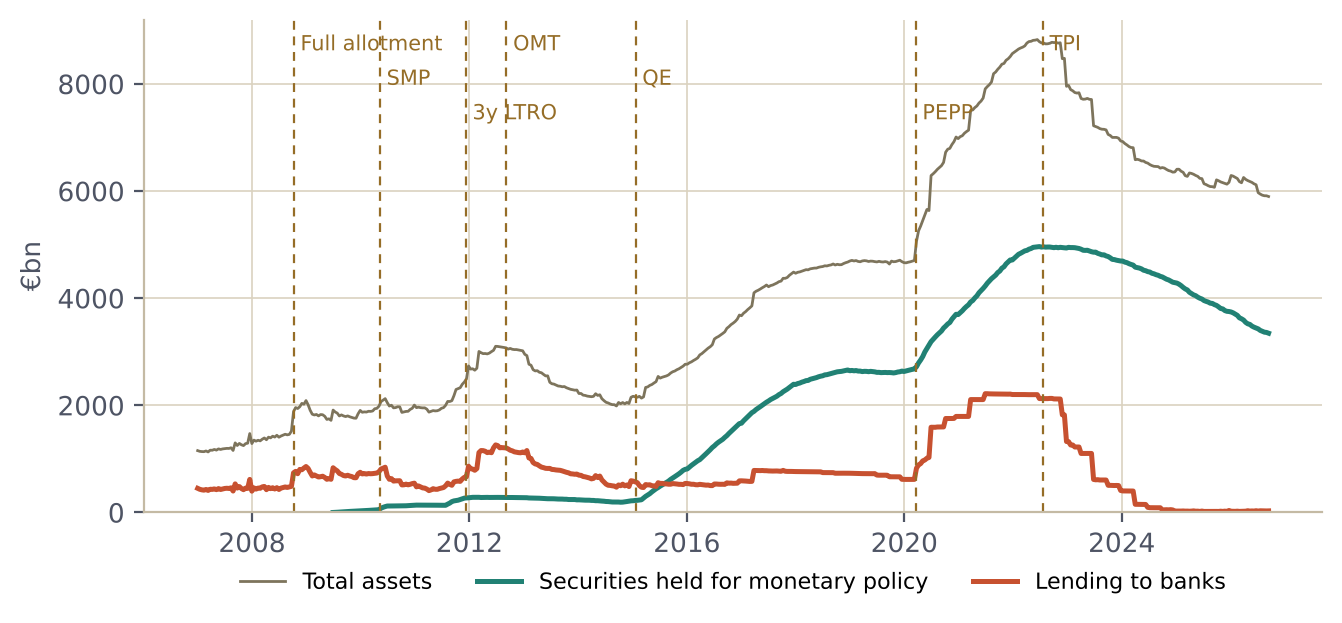
| Instrument | Since | Gate | Status | For France |
|---|---|---|---|---|
| Fixed-rate full allotment | Oct 2008 | Bank solvency, collateral | Live | Available: banks can fund OATs without limit at 2.65%. Protects bank funding, not the sovereign's price. |
| Collateral waivers | May 2010 | A programme on track | Live | Not needed: five to seven notches above the BBB- floor. Haircuts step up below A-. |
| 1y / 3y LTROs, TLTRO I–III | 2009 – 2021 | None | Expired Dec 2024 | Quickest indirect support; worked on Italy and Spain for three months in 2012. Structural LTROs promised in 2024, not yet in place. |
| SMP | May 2010 | Discretion; a private letter | Terminated 2012 | Will not return: no conditions, de facto seniority. |
| OMT | Sep 2012 | An ESM programme or precautionary line, requested by the country | Live, never used | The only instrument built for a sovereign under attack. Requires France to sign a memorandum approved by 20 governments and the Bundestag. |
| PSPP | Jan 2015 | Euro-area inflation outlook | Run-off | About €360bn of French bonds here, €600bn with PEPP; the Eurosystem is a net seller by redemption. Pausing run-off is the one step short of TPI. |
| PEPP | Mar 2020 | Pandemic | Run-off | Flexible reinvestment — the 'first line of defence' in 2022 — ended in December 2024. |
| TPI | Jul 2022 | Four criteria, incl. not failing an excessive deficit procedure; 'unwarranted, disorderly' dynamics | Live, never used | France is in an EDP. The door is open only while the Council has not found a failure to act — and a spread driven by a contested budget is, on the ECB's own test, warranted. |
| EFSF / ESM loans | 2010 / 2012 | Request, memorandum, unanimity | Live | €500bn against €3,460bn of debt and €340bn of issuance planned for 2027. France guarantees a fifth of it. |
| ESM credit lines | 2011 | As for a loan | Never used | The form a programme for a large country would take: undrawn, with the ECB buying. Nobody has ever asked. |
| Joint EU debt | 2020 | Unanimity, national ratifications | Winding down | Built for a symmetric shock. |
The courts set the edges. Gauweiler (CJEU, 2015) upheld OMT with safeguards. Weiss (CJEU, 2018) upheld QE, leaning on capital-key allocation and issuer limits. Karlsruhe (May 2020) declared Weiss ultra vires and singled out exactly those safeguards. A TPI purchase of one country's bonds would have none of them.
## France: the same grid
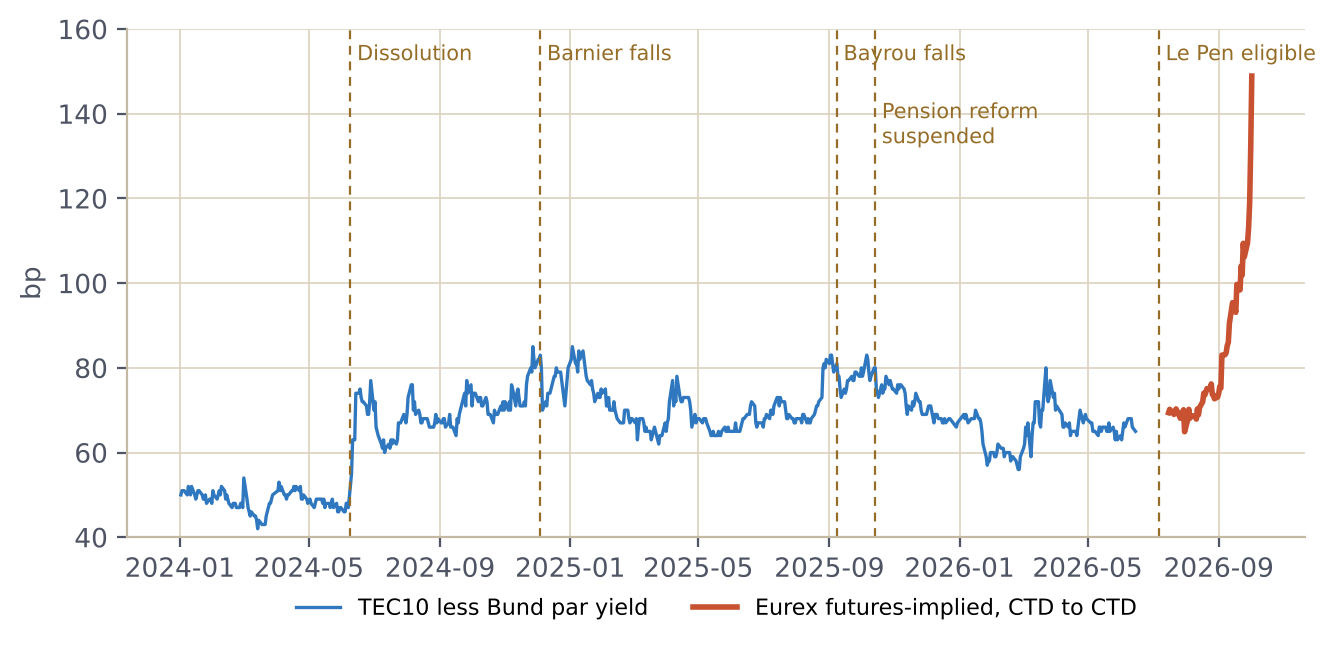
| Date | Event | Greek parallel |
|---|---|---|
| 9 Jun 2024 | Dissolution. Spread 47bp → 74bp in a week | A surprise consultation reprices the sovereign (Oct 2011) |
| 7 Jul 2024 | Three blocs, no majority | Greece, May 2012 |
| 26 Jul 2024 | Excessive deficit procedure opened | — |
| 4 Dec 2024 | Barnier censured over a €60bn consolidation; 10-year touches Greece's | Portugal, March 2011 — but France had market access |
| 14 Dec 2024 | Moody's to Aa3 | |
| 8 Sep 2025 | Bayrou loses a confidence vote on a €44bn plan, 364–194; Fitch to A+ | |
| 14 Oct 2025 | Pension reform suspended to survive censure; S&P to A+ three days later | Tsipras's pension bonus, Dec 2016 — punished by creditors within a week |
| 2 Feb 2026 | Third budget in a row adopted late, by 49.3 | |
| Mar 2026 | Energy shock; ECB raises rates in June and September | ECB hikes of April and July 2011 |
| 2 Jun 2026 | Moulin replaces Villeroy at the Banque de France | The same people recur |
| 7 Jul 2026 | Appeal court lets Le Pen run; she polls 31–37% | Syriza's lead through 2014 |
| 1 Oct 2026 | 2027 budget: €54bn, deficit 5.4% → 5.0%, record €340bn issuance. 10-year at 4.96%. Nagel and Moulin: do not count on the ECB | 'Not discussed', 6 May 2010 |
| 18 Apr 2027 | Presidential election, first round | Greece, 25 Jan 2015 |
## What the tape shows
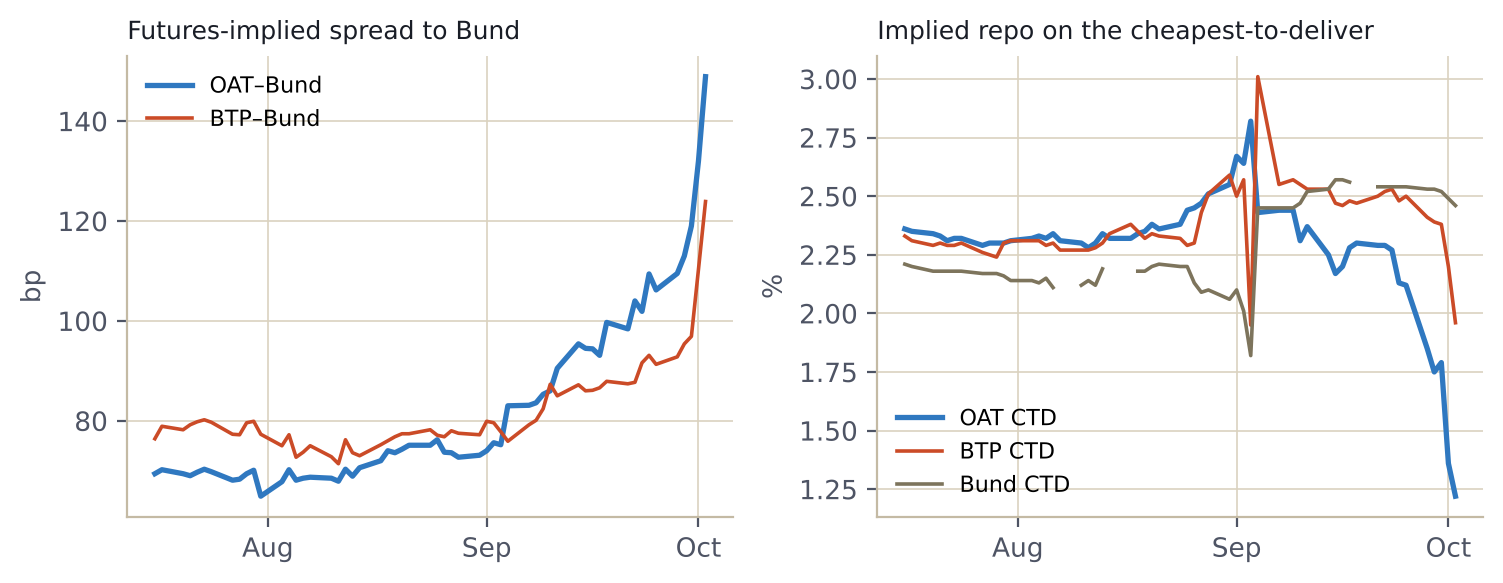
From the Eurex off-book tape — every EFP print in the OAT, Bund and BTP futures, 2,968 OAT prints over 57 sessions:
- **The spread.** OAT–Bund, futures-implied and CTD-to-CTD: 69bp on 16 Jul 2026, 65–76bp through August, 149bp on 2 Oct 2026. It widened 39bp in the last four sessions. On 1 October the tape reads 132bp, against 131–133bp quoted by Reuters for the benchmark spread.
- **France through Italy.** France has traded wider than Italy on this measure every session since 11 Sep. On 2 Oct: France 149bp, Italy 124bp.
- **Flight to quality.** On 2 Oct the Bund rallied 13bp while the OAT sold off 4bp. Until then both had been rising together.
- **The basis.** Implied repo on the OAT cheapest-to-deliver fell to 1.22% against 2.46% for the Bund and a 2.50% deposit rate; the gross basis widened to 0.42. The future is cheapening against the bond: hedges and shorts are going through futures first.
- **The curve.** Bonds that traded in both the first and last week moved 61 to 95bp higher — close to a parallel shift, slightly larger at the short end.
> [!WARNING]
> **Limits.** The tape is a block market, not a continuous quote. The spread is cheapest-to-deliver to cheapest-to-deliver and steps by roughly 5–8bp at the September roll. Crisis-era yields in this note are monthly averages, which flatten every peak. The daily French series ends in mid-June 2026 and the tape begins in mid-July. French events after June 2026 rest on a small number of wire reports.
## What higher rates cost France
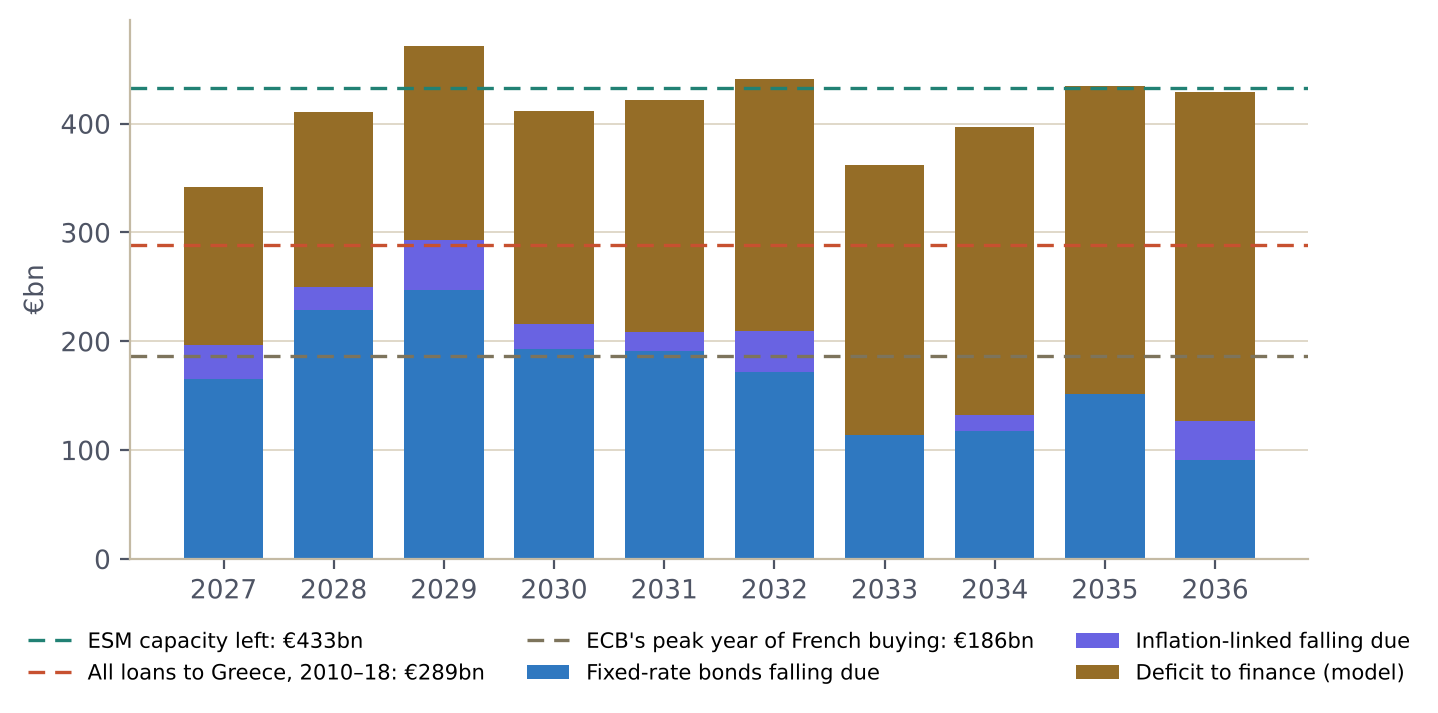
The State's negotiable debt was €2,904bn at 31 Aug 2026: 76 bonds and 27 bills, with an average life of 8 years and 142 days and an average coupon of 2.13% on the fixed-rate bonds. On 2 Oct 2026 new medium- and long-term borrowing cost about 4.62% — the Eurex tape's curve read at the maturities the Agence France Trésor issues — against 3.83% in mid-July. Each bond that matures is replaced at the new yield, and the deficit is borrowed at it too.
| Falls due in | €bn | Coupon, % | Costs now | At 4.62% | Added | Running total |
|---|---:|---:|---:|---:|---:|---:|
| 2027 | 196 | 1.70 | 4.0 | 9.1 | +5.1 | +5.1 |
| 2028 | 250 | 1.10 | 3.0 | 11.6 | +8.6 | +13.7 |
| 2029 | 293 | 2.11 | 6.7 | 13.6 | +6.9 | +20.5 |
| 2030 | 216 | 1.82 | 4.1 | 10.0 | +5.9 | +26.4 |
| 2031 | 209 | 1.41 | 3.1 | 9.7 | +6.6 | +33.0 |
| 2032 | 209 | 2.36 | 5.6 | 9.7 | +4.0 | +37.0 |
| 2033 | 114 | 3.28 | 3.7 | 5.3 | +1.5 | +38.6 |
| 2034 | 132 | 2.03 | 2.8 | 6.1 | +3.3 | +41.9 |
| 2035 | 152 | 3.70 | 5.6 | 7.0 | +1.4 | +43.3 |
| 2036 | 127 | 1.90 | 2.5 | 5.9 | +3.4 | +46.7 |
| 2037 and later | 727 | — | 18.1 | 33.6 | +15.6 | +62.2 |
Coupon: average on the fixed-rate bonds falling due, weighted by amount. Costs, added and running total: €bn a year. Costs now: coupons, plus 2% inflation on the indexed principal of linked bonds. Source: AFT bulletin; Eurex tape.
- **The wall.** €1,164bn falls due in 2027–2031. Replacing it at today's yield adds €33bn a year to the interest bill by 2031, before a euro of new deficit. The dearest year is 2028: €250bn at an average coupon of 1.10%, worth €8.6bn a year.
- **The bill.** The budget puts State debt service at €62.6bn in 2026 and €72.9bn in 2027. Held at the yields of 2 Oct with no further fiscal effort, the model gives €73bn in 2027, €133bn in 2031 and €208bn in 2036, 5.1% of GDP.
- **One point.** A permanent 100bp on the whole curve costs €3.1bn in the first year and €23.6bn a year by the fifth. The budget documents say 3.2 and 23.5. At nine years the model gives 47.7 against their 33.5, because it does not assume the deficit falls.
- **Inflation.** €314bn of the debt is indexed: each point of inflation costs €3.1bn a year.
- **Against revenue.** Interest took 4.2% of public revenue in 2025. On the same path it takes 8.8% in 2031 and passes Italy's 2012 peak of 10.7% in 2035. Greece's peak, in 2011, was 17.3%.
- **The deficit target.** A deficit of 3% in 2029 needs a primary balance 2.9 points of GDP better than the −2.1% implied by the 2027 budget: about €96bn a year. Each further 100bp adds about €17bn. The 2027 budget contains €54bn of measures.
- **The long run.** At the 2.0% the debt cost on average in 2025, a primary balance of −1.1% of GDP holds the debt ratio still. At today's issuance yield it takes +1.9%. France ran −2.9% in 2025: a gap of 4.8 points, €147bn, once the whole stock has repriced.
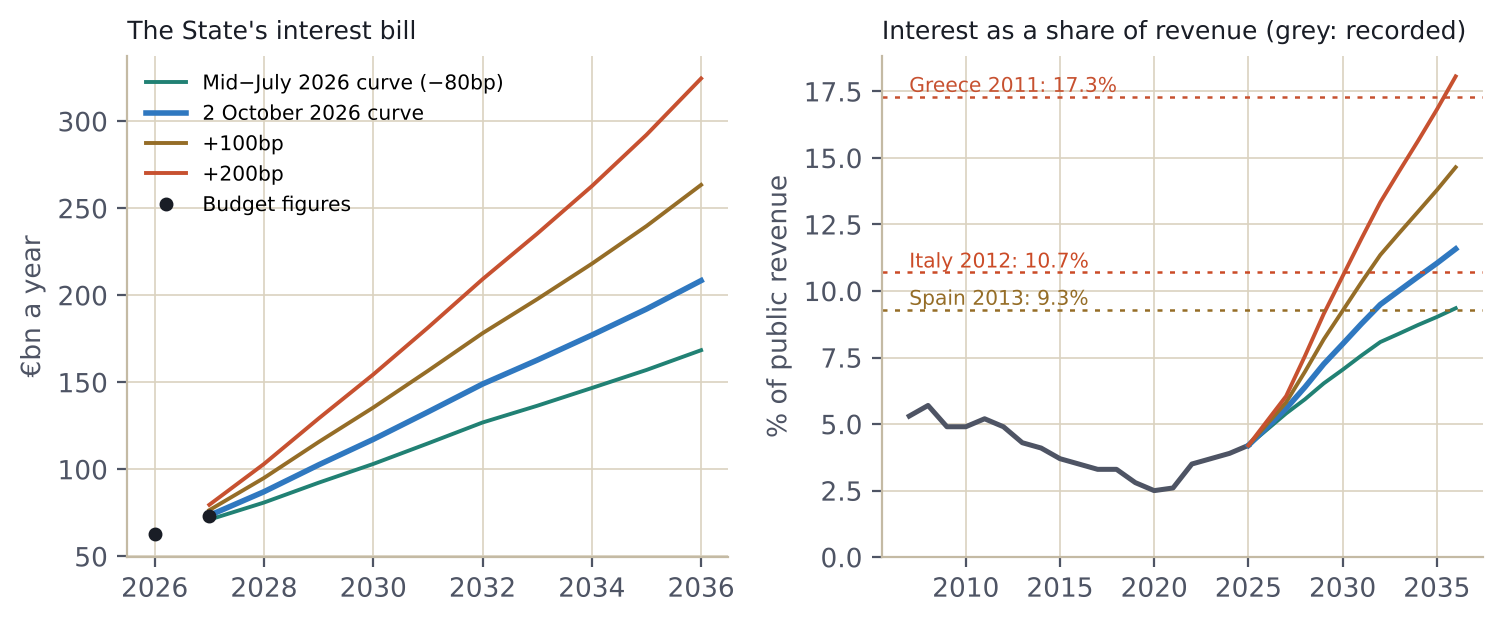
| Yields | Issue, % | 2027 | 2031 | 2036 | % GDP 2036 | Debt 2036 | Int/rev 2031 |
|---|---:|---:|---:|---:|---:|---:|---:|
| Mid−July 2026 curve (−80bp) | 3.82 | 71 | 115 | 168 | 4.1 | 142 | 7.6 |
| 2 October 2026 curve | 4.62 | 73 | 133 | 208 | 5.1 | 148 | 8.8 |
| +100bp | 5.62 | 77 | 157 | 263 | 6.4 | 156 | 10.3 |
| +200bp | 6.62 | 80 | 181 | 325 | 7.9 | 164 | 12.0 |
Interest: State debt charge, €bn a year. % GDP: the same in the last year. Debt: general government, % of GDP. Int/rev: general-government interest as a share of public revenue, %.
> [!WARNING]
> **A model, not a forecast.** Coupons accrue until each line matures, then the new-issue yield applies; bills pay the ECB deposit rate, 2.50%; inflation is 2%; nominal GDP grows 2.5% in 2026 and 3% a year after; the primary balance stays where the 2027 budget puts it. It is not the budget's accounting, has no buybacks and no feedback from yields to growth, and gives the 16% of public debt outside the State the State's average rate. The yields are those of one day. The site lets every one of these be moved.
## Who could buy French debt, and on what terms
Five rungs, from what already exists to what was built for much smaller countries. The higher the rung, the more it buys and the more it asks.
### 1. Banks fund at the ECB and hold the bonds — available now
- **Trigger.** None. It is the standing regime: banks get all the liquidity they bid for at a fixed rate against collateral, since October 2008, made permanent in March 2024.
- **Asks.** Nothing from the State. It asks French banks and insurers to add to holdings that are already a fifth of the debt: banks 10.5%, insurers 9.6% in March 2026. Non-residents hold 57.5%.
- **Size.** No limit on the ECB's side. At 2.65% on the main operation against 4.82% on a ten-year OAT, the carry is 217bp.
- **Effect.** The two three-year operations of December 2011 and February 2012 lent €1.02tn. The Italian spread fell from 519bp in November 2011 to 322bp in March 2012 and was back at 476bp in July: it bought months, not a floor.
- **Catch.** It moves the risk onto French bank balance sheets, the loop that banking union was built to cut. The standard operations run for one week and three months, not three years.
### 2. Stop the run-off, or reinvest — possible, indirect
- **Trigger.** A monetary-policy decision for the euro area as a whole. It needs a stance argument — that shrinking the balance sheet is tightening more than intended — not a French one. No request, no conditions.
- **Asks.** Nothing.
- **Size.** The Eurosystem holds about €600bn of French public-sector bonds. They ran off by €87bn in 2025 and by €63bn in the first 8 months of 2026. Full reinvestment would take about €87bn a year off what private buyers must absorb, 26% of the 2027 programme. It adds no new buyer, and by capital key France is 19.8% of anything bought for the euro area as a whole.
- **Effect.** ECB staff put the stock effect of the whole purchase programme at 95bp off the ten-year term premium by mid-2018, with the Eurosystem's share of the four largest countries' bonds up from under 7% to about 23%: roughly 6bp per point of the stock. On that arithmetic €87bn, 3.0% of the State's debt, is of the order of 18bp.
- **Catch.** The ECB raised rates in June and September. Buying bonds while tightening has to be argued as protecting transmission, which is what the next rung is for.
### 3. Transmission Protection Instrument — gated
- **Trigger.** The Governing Council judges that French financing conditions are deteriorating in a way 'not warranted by country-specific fundamentals' and that the dynamics are 'unwarranted, disorderly'. Its own decision; France does not ask. Analysts quoted by Reuters expect it only if spreads widen across several countries at once.
- **Asks.** Four criteria, as 'an input'. (1) EU fiscal rules: France has been in an excessive deficit procedure since July 2024 and passes only while it is not found to have failed to take 'effective action'. On 3 June 2026 the Commission held the procedure in abeyance: net expenditure grew 0.7% in 2025 against a 0.8% ceiling, is projected at 1.4% in 2026 against 1.2%, and cumulatively 5.4% against 5.8%. The ceilings are 1.2% in 2027 and 2028 and 1.1% in 2029, with the deficit under 3% by 2029. (2) No excessive imbalance: met; France was not selected for an in-depth review in 2026. (3) Sustainable debt: the Commission sees 'high fiscal sustainability risks in the medium term'. (4) Recovery-plan commitments: 'broadly on track', but the 2023 pension reform is suspended until January 2028.
- **Effort.** A 3% deficit in 2029, from the 5.0% of the 2027 budget, needs a primary balance 2.9 points of GDP better than in 2027 — about €96bn a year by 2029 — at today's yields, because interest takes back part of every saving. Each further 100bp adds about €17bn. The 2027 budget's €54bn of measures, €43bn of them new, is the first instalment.
- **Size.** No ex ante limit. Public-sector bonds with one to ten years to run: €1,737bn of French State debt, 60% of the stock. Purchases are to leave 'no persistent impact' on the balance sheet, so something else would be sold or allowed to mature.
- **Effect.** Never used. It was commissioned on 15 June 2022 with the Italian spread at 219bp on the month; the spread was 228bp in July, 235bp in October and 217bp in December. It stopped the widening and did not reverse it.
- **Catch.** A spread that follows a contested budget and an election is, on the ECB's own test, warranted. Governors Nagel and Moulin have both said not to count on it.
### 4. ESM credit line, then OMT — gated
- **Trigger.** France asks. In an excessive deficit procedure it would not qualify for the lighter precautionary line, so it is the enhanced one, with a memorandum. The ESM decides by mutual agreement of the finance ministers, the Bundestag voting first. Only then can the ECB consider OMT, and it decides separately.
- **Asks.** 'Strict and effective conditionality' written into a memorandum: dated fiscal and structural commitments, enhanced surveillance, IMF involvement 'sought'. No precautionary memorandum has ever been written. Spain weighed exactly this in autumn 2012 and did not ask.
- **Effort.** The only measure of what a memorandum demands is what the signed ones delivered: see the table of programme turns below. Spain, with a bank-only programme and a deficit procedure, moved its primary balance by 5.0 points in four years — €153bn at French scale.
- **Size.** OMT: no limit, in bonds with one to three years to run — €553bn of French State debt, 19% of the stock, fully sterilised. The ESM has €433bn of lending capacity left, 1.3 years of French medium- and long-term issuance, and may take at most half of any auction.
- **Effect.** ECB staff estimate that the announcement alone took about 200bp off Italian and Spanish two-year yields and about 100bp off ten-year yields; French and German yields were 'largely unaffected'. On the monthly averages the Italian spread went from 476bp in July 2012 to 324bp in December and the Spanish from 555bp to 404bp. Not one bond was bought.
- **Catch.** It needs a French government to sign a memorandum six months before a presidential election, and twenty other governments to approve it.
### 5. A full programme: ESM and IMF loans — too small
- **Trigger.** Loss of market access: an auction that fails, or yields at which the State will not borrow.
- **Asks.** A macroeconomic adjustment programme with quarterly reviews by the Commission, the ECB and the IMF.
- **Effort.** Under their programmes the primary balance moved by 13.7 points of GDP in Greece, 12.2 in Ireland and 8.5 in Portugal. At French scale that is €421bn, €374bn and €261bn a year.
- **Size.** The ESM has €433bn left. The French State needs €340bn in 2027 and about €1,223bn over 2027–29. Ireland's and Portugal's programmes were 40% and 44% of their GDP; the same share of French GDP is €1,239bn to €1,358bn. France is also 19.8% of the euro-area capital key on which the ESM's own shares are based.
- **Effect.** For Greece the loans' low rates and long maturities are worth, on the ESM's estimate, €12bn a year — 6.7% of Greek GDP in 2017.
- **Catch.** The mechanism was sized for economies a tenth of France's. That is why the practical question is whether the ECB buys, not whether the ESM lends.
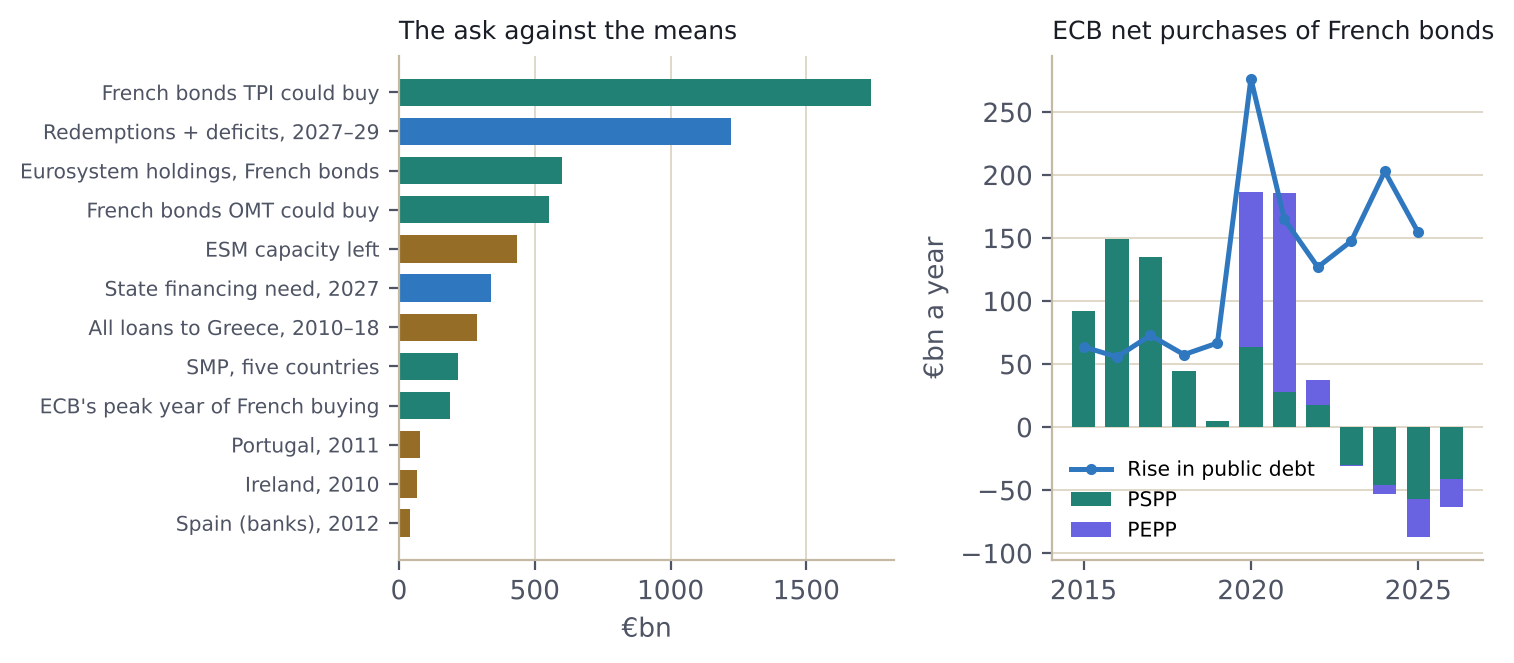
The ECB's instruments are not short of room: €553bn of French State debt falls in OMT's one-to-three-year range and €1,737bn in TPI's one-to-ten. The rescue funds are: the ESM has €433bn left against €1,223bn of French redemptions and deficits over 2027–29. And the buyer of last resort has become a seller. In 2020 and 2021 the Eurosystem bought €372bn of French public-sector bonds, 84% of the rise in public debt. In 2025 debt rose by €154bn while the Eurosystem let €87bn run off, leaving €241bn for everyone else.
### What each programme did to spreads
| Programme | Decided | Bought | Condition | 10-year spread, before → after | Reading |
|---|---|---|---|---|---|
| SMP, first wave | 10 May 2010 | Greek, Irish and Portuguese bonds; €218bn across five countries by 2012 | None attached to the purchases | Greece 477 → 835bp; Portugal 172 → 296bp; Ireland 170 → 295bp | Purchases without a commitment: Greek spreads kept widening. |
| SMP, Italy and Spain | 7 Aug 2011 | €102.8bn of Italian and €44.3bn of Spanish bonds held at end-2012 | A confidential letter to each government | Italy 272 → 519bp; Spain 308 → 432bp | ECB staff find about 3bp at five years for each 0.1% of the debt bought, and 'large' announcement effects. The spread still doubled in four months. |
| OMT | 6 Sep 2012 | Nothing | An ESM programme, on request | Italy 476 → 324bp; Spain 555 → 404bp; France 104 → 71bp | An unlimited commitment with conditions did what €218bn of purchases had not. |
| PEPP | 18 Mar 2020 | €123bn of French public bonds in 2020; €186bn with the PSPP | None; flexible across countries | Italy 225 → 155bp; Spain 127 → 82bp; France 51 → 35bp | Buying at scale, for every country, when the shock was nobody's fault. |
| TPI | 21 Jul 2022 | Nothing | Four eligibility criteria | Italy 219 → 217bp; Spain 118 → 100bp; France 61 → 54bp | Capped the Italian spread near its June level; did not lower it. |
Ten-year yields over Germany, monthly averages (ECB), in the month before the decision and a few months after.
### What a programme asks
| Programme | Lent | % GDP | French scale | Primary balance | Turn | French scale |
|---|---:|---:|---:|---:|---:|---:|
| Greece, three programmes, 2010–18 | 288.7 | 129 | 3,963 | −10.3 → +3.4 | +13.7 | 421 |
| Ireland, 2010–13 | 67.5 | 40 | 1,239 | −11.9 → +0.3 | +12.2 | 374 |
| Portugal, 2011–14 | 78.0 | 44 | 1,358 | −8.5 → 0.0 | +8.5 | 261 |
| Spain (banks only), 2012–13 | 41.3 | 4 | 122 | −7.2 → −2.2 | +5.0 | 153 |
| France: to a 3% deficit in 2029, today's yields | — | — | — | −2.1 → +0.8 | +2.9 | 96 |
| France: measures in the 2027 budget | — | — | — | — | +1.7 | 54 |
Lent: €bn, and as a share of the country's GDP in the year the programme was agreed; French scale: the same share of French GDP in 2026, €bn. Primary balance: general-government balance plus interest payable, % of GDP (Eurostat), from the year before the programme to the year after the last bank-rescue costs passed through; turn in points of GDP; French scale: the same turn in €bn a year.
### What a backstop is worth
| Yields lower by | Year 1 | Year 3 | Year 5 | Year 10 | Five years, total |
|---|---:|---:|---:|---:|---:|
| 25bp | −0.8 | −3.2 | −5.7 | −12.9 | −16 |
| 50bp | −1.5 | −6.4 | −11.4 | −25.4 | −32 |
| 100bp | −3.0 | −12.8 | −22.5 | −49.5 | −64 |
€bn a year off the State's interest bill, from the model above. For scale: reinvesting the run-off is of the order of 18bp on the stock-effect arithmetic of the ECB's own staff; the OMT announcement took about 100bp off Italian and Spanish ten-year yields.
> [!IMPORTANT]
> **Reading.** The first two rungs ask nothing of France and are worth tens of basis points. The steps that took a hundred or more off spreads came with a signature, or with a shock that was nobody's fault. On this model a hundred basis points is worth €22.5bn a year after five years; the path to a 3% deficit, which is what keeps the Transmission Protection Instrument legally open, costs €96bn a year by 2029. A backstop does not replace the effort. At best it takes about 23% off its price, and every instrument above the second rung is conditional on the effort being made first.
## What would have to be true for the ECB to act
1. **A budget.** Every ECB move in 2010–2020 followed a government move: a backstop (May 2010), a fiscal compact (December 2011), banking union (June 2012), a recovery fund (July 2020). For France the equivalent is the 2027 budget adopted, by whatever route.
2. **No finding of 'no effective action'.** TPI's first criterion excludes a country assessed as having failed to act under its excessive deficit procedure. The Council has not made that finding: the Commission's assessment of 3 June 2026 holds the procedure in abeyance, with net expenditure growth projected at 1.4% in 2026 against a ceiling of 1.2%. A rejected budget or a breach of the expenditure path would invite it.
3. **Contagion.** The ECB has never intervened for one country alone. Italy at 110bp and Belgium at 80bp on 1 October are the numbers that would turn a French problem into a transmission problem — and make a decision defensible in Karlsruhe.
Short of that, the available steps are indirect: pausing the run-off of the bond portfolios, and term refinancing that lets banks carry the paper. The first contradicts two rate rises; the second tightens the bank–sovereign loop.
## What to watch
- The 49.3 and censure sequence on the budget, through December. Three routes — 49.3, a special law, ordinances — each end in a different government or no budget.
- The Council's next assessment under the excessive deficit procedure.
- Italy's spread relative to France's.
- The OAT futures basis and implied repo, where stress showed first.
- Rating reviews: France is at A+ on S&P and Fitch; the collateral haircut step is below A-.
- First-round polls, and what the front-runner says about the 2023 pension reform and the EU budget.
## Method and sources
Series are pulled through `econdata` from the ECB Data Portal (long-term interest rates, weekly financial statement, TARGET balances, bank balance sheets, purchase-programme breakdowns), Eurostat (EDP notification, balance of payments) and DBnomics (Banque de France TEC10, Bundesbank par yields). The French State's debt is taken line by line from the Agence France Trésor monthly bulletin; the debt-cost model is `pipeline/debt.py` in the site's repository, and the same model runs in the page. The Eurex tape comes from the `eurex-offbook` archive. The event ledger is written from ECB press releases, Eurogroup and Euro Summit statements, court press releases, the ESM's programme pages, the IMF's 2013 ex post evaluation and 2016 IEO report, Zettelmeyer, Trebesch and Gulati (2013) on the restructuring, Wikipedia chronologies and Reuters wire copy. The full ledger — 121 dated entries for the euro-area crisis and 27 for France, each with its sources — is at greece.bzhmacro.com.